
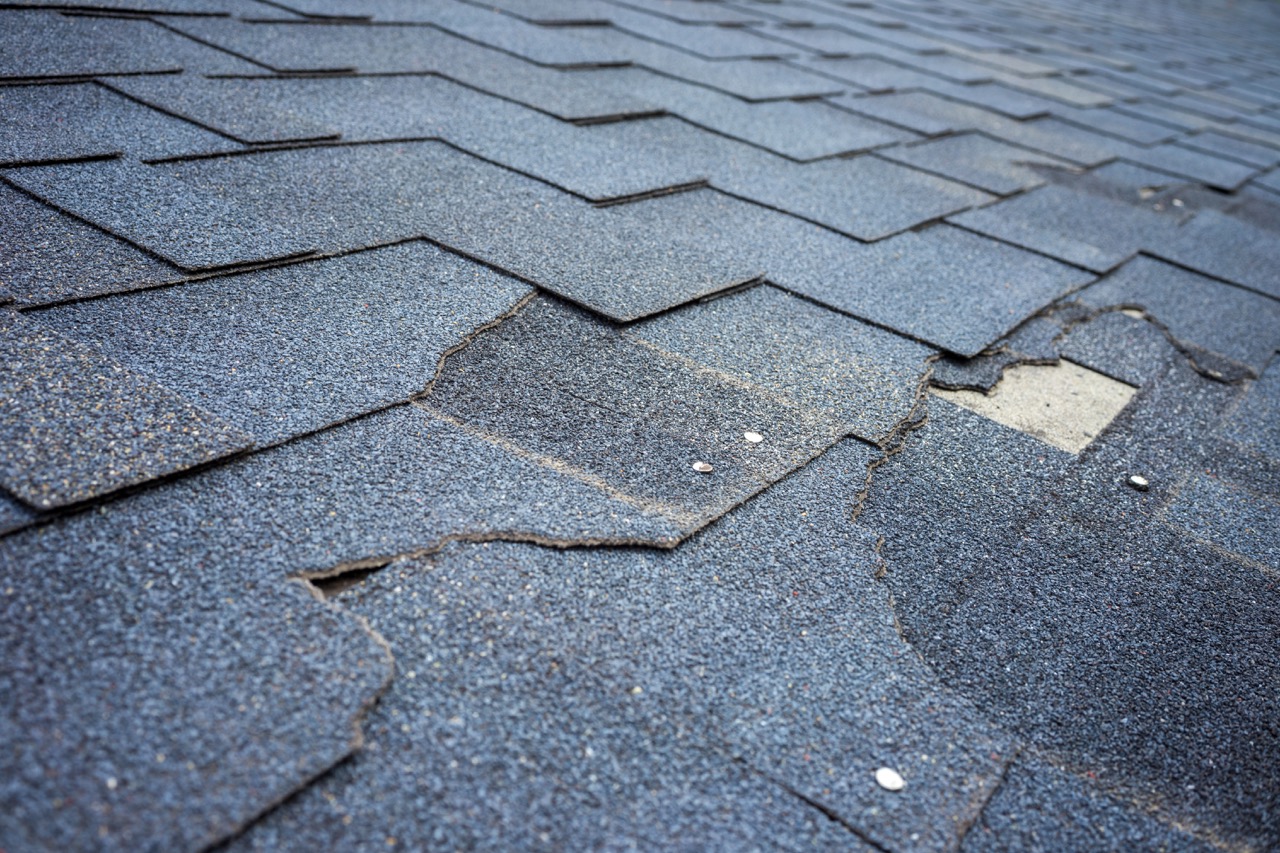
What Is Roof Surface Loss Settlement in Florida Insurance Policies?
Most Florida homeowners do not think about their insurance policy language until roof damage actually happens. After a storm or hurricane, many people discover unfamiliar terms buried deep in their policy documents. One term that surprises many Miami and South Florida homeowners is roof surface loss settlement. This provision can significantly limit how much your insurer pays after storm-related roof damage occurs.
Instead of covering a full roof replacement, your policy may pay far less than you expected. In this blog, you will learn exactly what roof surface loss settlement means, how it affects your payout, and what to watch for during a claim.
What Is Roof Surface Loss Settlement?
Roof surface loss settlement is a policy provision that limits how much an insurer pays for roof damage based on factors like age, depreciation, or specific policy calculations. In simple terms, it means your insurance company may not pay for a full roof replacement even after a covered storm event.
Instead, they calculate a reduced payout based on your roof’s current condition and age. This is very different from replacement cost coverage, which pays to restore your roof to its pre-storm condition. Actual cash value coverage deducts depreciation before paying out. Roof surface loss settlement provisions go even further by applying additional policy-specific limitations that reduce your final settlement amount significantly.
Why Florida Insurance Policies Include Roof Surface Loss Settlement Provisions
Florida’s storm history has pushed insurance companies to restructure how they handle roof damage claims across the state. Insurance companies often include these policy terms for several financial and risk-related reasons:
- Rising hurricane-related claim costs that have strained insurance companies operating across Florida for years
- Aging roofs across Florida properties that increase the likelihood of damage during every storm season
- Increased roof replacement expenses driven by rising material and labor costs throughout Miami-Dade and Broward counties
- Frequent storm damage claims in Miami and South Florida following active Atlantic hurricane seasons each year
- Efforts to reduce insurance company losses by limiting payout obligations tied to older or partially worn roofing systems
- Policy restructuring after major hurricane seasons that pushed insurers to add new limitations protecting their financial exposure
How Roof Surface Loss Settlement Affects Homeowners
For Miami and South Florida homeowners, a roof surface loss settlement provision can mean receiving far less than you need to fully repair your home. Your insurer may offer only enough to cover partial repairs instead of a complete roof replacement. Some damage may be classified as cosmetic and excluded from coverage entirely under this type of provision.
Interior water damage, structural components, and supporting materials are also sometimes left out of the settlement calculation. The financial gap between what your insurer pays and what repairs actually cost can be substantial. Many North Miami and South Florida homeowners end up covering thousands of dollars out of pocket that they assumed their policy would handle.
Signs Your Roof Settlement May Be Lower Than It Should Be
Low settlements are not always easy to recognize right away. Many homeowners only notice the gap after contractors begin assessing the real scope of repairs needed. Here are the most common signs that your roof surface loss settlement may not be fair:
Your Settlement Is Much Lower Than Contractor Estimates
If multiple licensed contractors quote significantly more than your insurer paid, that gap is a serious red flag. The difference between insurer payment and actual repair costs can reach tens of thousands of dollars in South Florida. A large gap almost always warrants a closer review of your settlement calculation.
The Insurance Company Applies Heavy Depreciation
Older roofs in Miami and South Florida are frequently subject to steep depreciation deductions before any payout is issued. Even a roof with several years of life remaining can receive a dramatically reduced settlement. Heavy depreciation is one of the most common ways a roof surface loss settlement ends up lower than expected.
Only Part of the Roof Damage Is Covered
Your settlement may cover visible shingle damage while leaving out interior leaks, water intrusion, or structural components. Missing coverage for ceilings, insulation, and underlayment is common in disputes involving roof surface loss settlement provisions. If key damage types are absent from your settlement breakdown, your payout may be incomplete.
Your Policy Language Is Difficult to Understand
Complex policy wording is sometimes used to obscure the real limitations of your roof coverage. If you cannot clearly understand what your policy does and does not cover, you may be missing important exclusions. Difficult language around roof surface loss settlement provisions often hides significant reductions that affect your final payout.
What Florida Homeowners Should Review in Their Insurance Policy
Understanding your policy before a claim occurs puts you in a much stronger position after storm damage happens. Review these key sections of your Florida homeowner insurance policy carefully:
- Roof settlement provisions that describe how damage is calculated and what limitations apply to your coverage
- Replacement cost endorsements that may upgrade your coverage from actual cash value to full replacement cost
- Actual cash value clauses that reduce payouts by deducting depreciation based on your roof’s age and condition
- Hurricane deductibles which are often separate from standard deductibles and significantly reduce net claim payments
- Cosmetic damage exclusions that allow insurers to deny coverage for damage they classify as non-structural or superficial
- Roof age restrictions that limit or eliminate coverage for roofs beyond a certain age in Florida policies
- Claim reporting deadlines that must be met to preserve your right to file or supplement a roof damage claim
Can You Challenge a Low Roof Settlement in Florida?
Florida homeowners are not always required to accept the first settlement offer their insurance company presents. If your roof surface loss settlement seems far too low, you may have options worth exploring. Filing a supplemental claim is one path available when new or missed damage is discovered after your initial payout.
Requesting an independent inspection from a licensed roofing contractor can provide a second professional opinion on the damage scope. A legal review of your policy language may also reveal that the insurer misapplied the roof surface loss settlement provision in your case. You may have legal options depending on the specific circumstances of your claim and what your policy actually covers.
Why Roof Claim Disputes Are Common in Miami and South Florida
Miami and South Florida experience some of the most intense hurricane and tropical storm activity in the entire country. After major weather events, insurance companies receive thousands of roof damage claims from homeowners across Miami-Dade, Broward, and surrounding counties. This high volume increases the risk of rushed inspections, incomplete assessments, and undervalued settlements for individual homeowners.
Roofing costs in North Miami and throughout South Florida have also risen sharply, widening the gap between insurer estimates and real contractor quotes. At the same time, insurers operating in Florida have added more policy restrictions to limit their financial exposure in high-risk coastal areas. These combined pressures make roof claim disputes increasingly common for South Florida homeowners after every storm season.
How CMS Law Group Helps Florida Homeowners With Roof Claim Disputes
CMS Law Group reviews insurance policies and settlement offers to help homeowners understand exactly what they are entitled to receive. Our attorneys carefully examine roof surface loss settlement provisions and identify where insurers may have misapplied policy language. We help Miami and South Florida homeowners understand their coverage limitations so they can make informed decisions.
Our team investigates delayed, denied, and underpaid roof claims with attention to detail and a commitment to client advocacy. Every client receives direct communication and personalized support throughout the entire process. Our approach reflects the values that define CMS Law Group: experience, diligence, and trust in every case we handle.
Do Not Let Confusing Policy Language Cost You the Payout You Deserve
Insurance policy language can be genuinely difficult to understand, even for experienced homeowners. Reviewing your settlement carefully before accepting payment is one of the most important steps you can take. Understanding your rights after roof damage in Florida gives you the best chance of receiving a fair outcome. Contact CMS Law Group if you believe your roof damage claim was unfairly delayed, denied, or underpaid in Miami or South Florida.
CMS Law Group
12955 Biscayne Blvd. Suite 201
North Miami, FL 33181
(866) 345-2033
info@cmslawgroup.com


